Current as of October 2026. Government programs, tax rules and prices change. Check the official sources listed at the end of this page before making a decision, and confirm details with a licensed advisor.
What the Chambers Plan is, in brief
The Chambers Plan, formally known as the Chambers of Commerce Group Insurance Plan, is a group benefits program built for small businesses across Canada. Its website describes it, as of October 2026, as a not-for-profit plan for companies with teams of 1 to 50+, endorsed by more than 700 chambers of commerce and boards of trade, and chosen by more than 32,000 businesses. It says it has supported Canada's business community since 1971.
Two names come up when you read about it. The Chambers of Commerce Insurance Corporation of Canada (CCICC) is described as being run by a board that represents regions across the country. Johnston Group, which the plan describes as 100% Canadian, independent, family-owned and based in Winnipeg, administers the plan.
GroupBenefitPlans.ca is not affiliated with the Chambers Plan, Johnston Group, the CCICC or any chamber of commerce, does not sell the plan, and is not endorsed by it. This page summarizes publicly available information as of October 2026 so employers can ask better questions. Plan details change, so confirm current terms with a licensed advisor or directly with the plan.
What the plan publicly offers employers
As of October 2026, the Chambers Plan website lists these core coverage areas for employers:
- Group health: prescription drugs, vision care and paramedical services such as chiropractors, massage therapists, physiotherapists and psychologists, plus travel health coverage. Our page on extended health benefits explains how this category usually works.
- Dental coverage: the benefit most employees use first, from a routine cleaning onward. See group dental coverage for the basics.
- Group life insurance: the plan's administrator page says optional life coverage is available in units of $10,000 up to $500,000 for employees and spouses.
- Disability insurance: short-term disability described as paying benefits for up to 6 months, and long-term disability that can last several years or until age 65. The plan states that businesses with three or more employees qualify for guaranteed disability coverage.
- Critical illness insurance: described by the plan as a flexible add-on rather than standard coverage.
- Spending accounts and add-ons: the plan also lists a Health Spending Account, a Lifestyle Spending Account and an Employee Assistance Program among its flexible add-ons. See health spending accounts for how these generally work.
Virtual care, mental health and extras
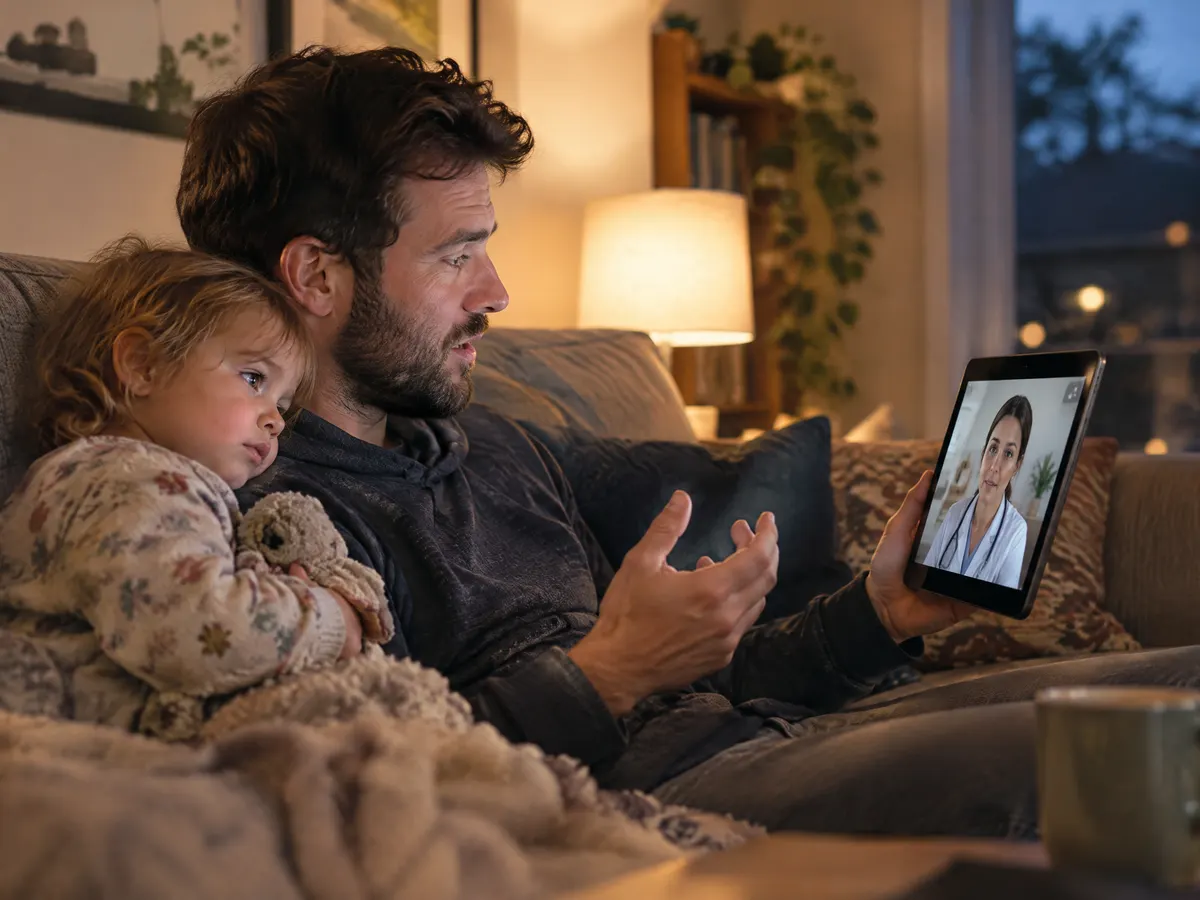
Beyond the core benefits, the plan's website describes telemedicine, specialist access and a Mental Health Navigator service delivered through Teladoc Health Canada, along with myStrength self-guided programs. It also lists Business Assistance Services, which it describes as professional coaching, human resource guidance, legal and financial guidance and a digital business library, and says these built-in supports come at no extra cost as of October 2026. An Employee Assistance Program is listed separately as a flexible add-on.
For a small team, these extras can matter as much as the drug plan: a parent who can talk to a doctor by video at night, or an owner who needs a quick HR answer. If these features are a priority, our pages on virtual care benefits and employee assistance programs explain what to compare across providers.
Pooling, administration and leaving the plan
The Chambers Plan describes itself as a not-for-profit, pooled plan. In a pooled arrangement, the claims of many small employers are grouped together, so one costly year in a five-person firm does not have to drive that firm's renewal on its own. Our guide to pooled vs. experience-rated benefits covers the trade-offs. The plan's homepage states that its average renewal over the last decade has been under 5%; that is the plan's own claim, and your actual renewal will depend on your group and the coverage you choose.
For day-to-day administration, employers use an online platform called my-benefits®, which the plan says lets administrators add and manage employees, update earnings and calculate payroll deductions. The plan also lists a Retiree Plan and a program called ContinYou, which it describes as guaranteed individual health and dental coverage for employees and dependents leaving Chambers Plan health and dental coverage, provided they apply within 60 days of their group coverage ending. For more on this situation in general, see coverage after leaving a group plan.
Plan members with questions about claims, cards or logins should go directly to the official Chambers Plan website at chamberplan.ca or contact the plan administrator. GroupBenefitPlans.ca cannot access accounts or help with claims.
How to evaluate the Chambers Plan for your business
The plan's website says a local Chambers Plan advisor will follow up with a free quote. Whether you go that route or compare it with other options, it helps to look at the same things you would with any provider:
- Fit for your size: a plan designed for 1 to 50+ employees may suit a small team well; a growing mid-sized firm may also want to compare options built for larger groups.
- Coverage levels: drug coverage, paramedical maximums, dental recall frequency and vision amounts vary by the options you choose.
- Eligibility rules: ask how waiting periods, part-time staff and owner coverage work for your group.
- Renewal history and method: ask how pooled rates are set and how your renewal will be explained to you.
- Flexibility: ask about health or wellness spending accounts and how optional benefits are added.
- Employee experience: how claims are submitted, how quickly they are paid, and what digital tools members get.
Questions to ask a licensed advisor
A licensed benefits advisor can walk you through the Chambers Plan alongside other providers, using your actual census and budget. Useful questions include: Is chamber of commerce membership required for my business, and if so, what does it cost? What are the guaranteed issue limits for life and disability at my group size? Which benefits are optional add-ons, and what do they add to the premium? How does this plan compare with an insurer's small-group plan or a pooled benefits plan from another provider?
If you would like an independent second opinion, you can get matched with a licensed benefits advisor who can compare the Chambers Plan with other options on your behalf.
Common questions
Who runs the Chambers Plan?
As of October 2026, the plan's website says it is a not-for-profit plan, that the Chambers of Commerce Insurance Corporation of Canada is run by a board representing regions across the country, and that Johnston Group, based in Winnipeg, administers the plan.
Can a business with one employee get the Chambers Plan?
The plan describes itself as built for companies with teams of 1 to 50+. Eligibility details, including how owners and part-time staff are treated, should be confirmed with a licensed advisor or the plan directly.
Do I need to be a chamber of commerce member?
As of October 2026, the plan's homepage does not present chamber membership as a prerequisite; it says joining the Chambers Plan also connects you to your local chamber of commerce and its networking and professional development opportunities. Ask an advisor or your local chamber how membership applies to your business.
What happens to employee coverage if someone leaves?
The plan lists ContinYou, described as guaranteed individual health and dental coverage for people previously covered under its health and dental program, if they apply within 60 days of group coverage ending (as of October 2026).
Is GroupBenefitPlans.ca part of the Chambers Plan?
No. GroupBenefitPlans.ca is an independent referral and information service with no affiliation to the Chambers Plan, Johnston Group or any chamber of commerce. For member account or claims help, use the official chamberplan.ca website.
Sources and further reading
GroupBenefitPlans.ca is a referral and information service. Advice and coverage are provided by the licensed professional and relevant providers. An enquiry does not activate insurance.